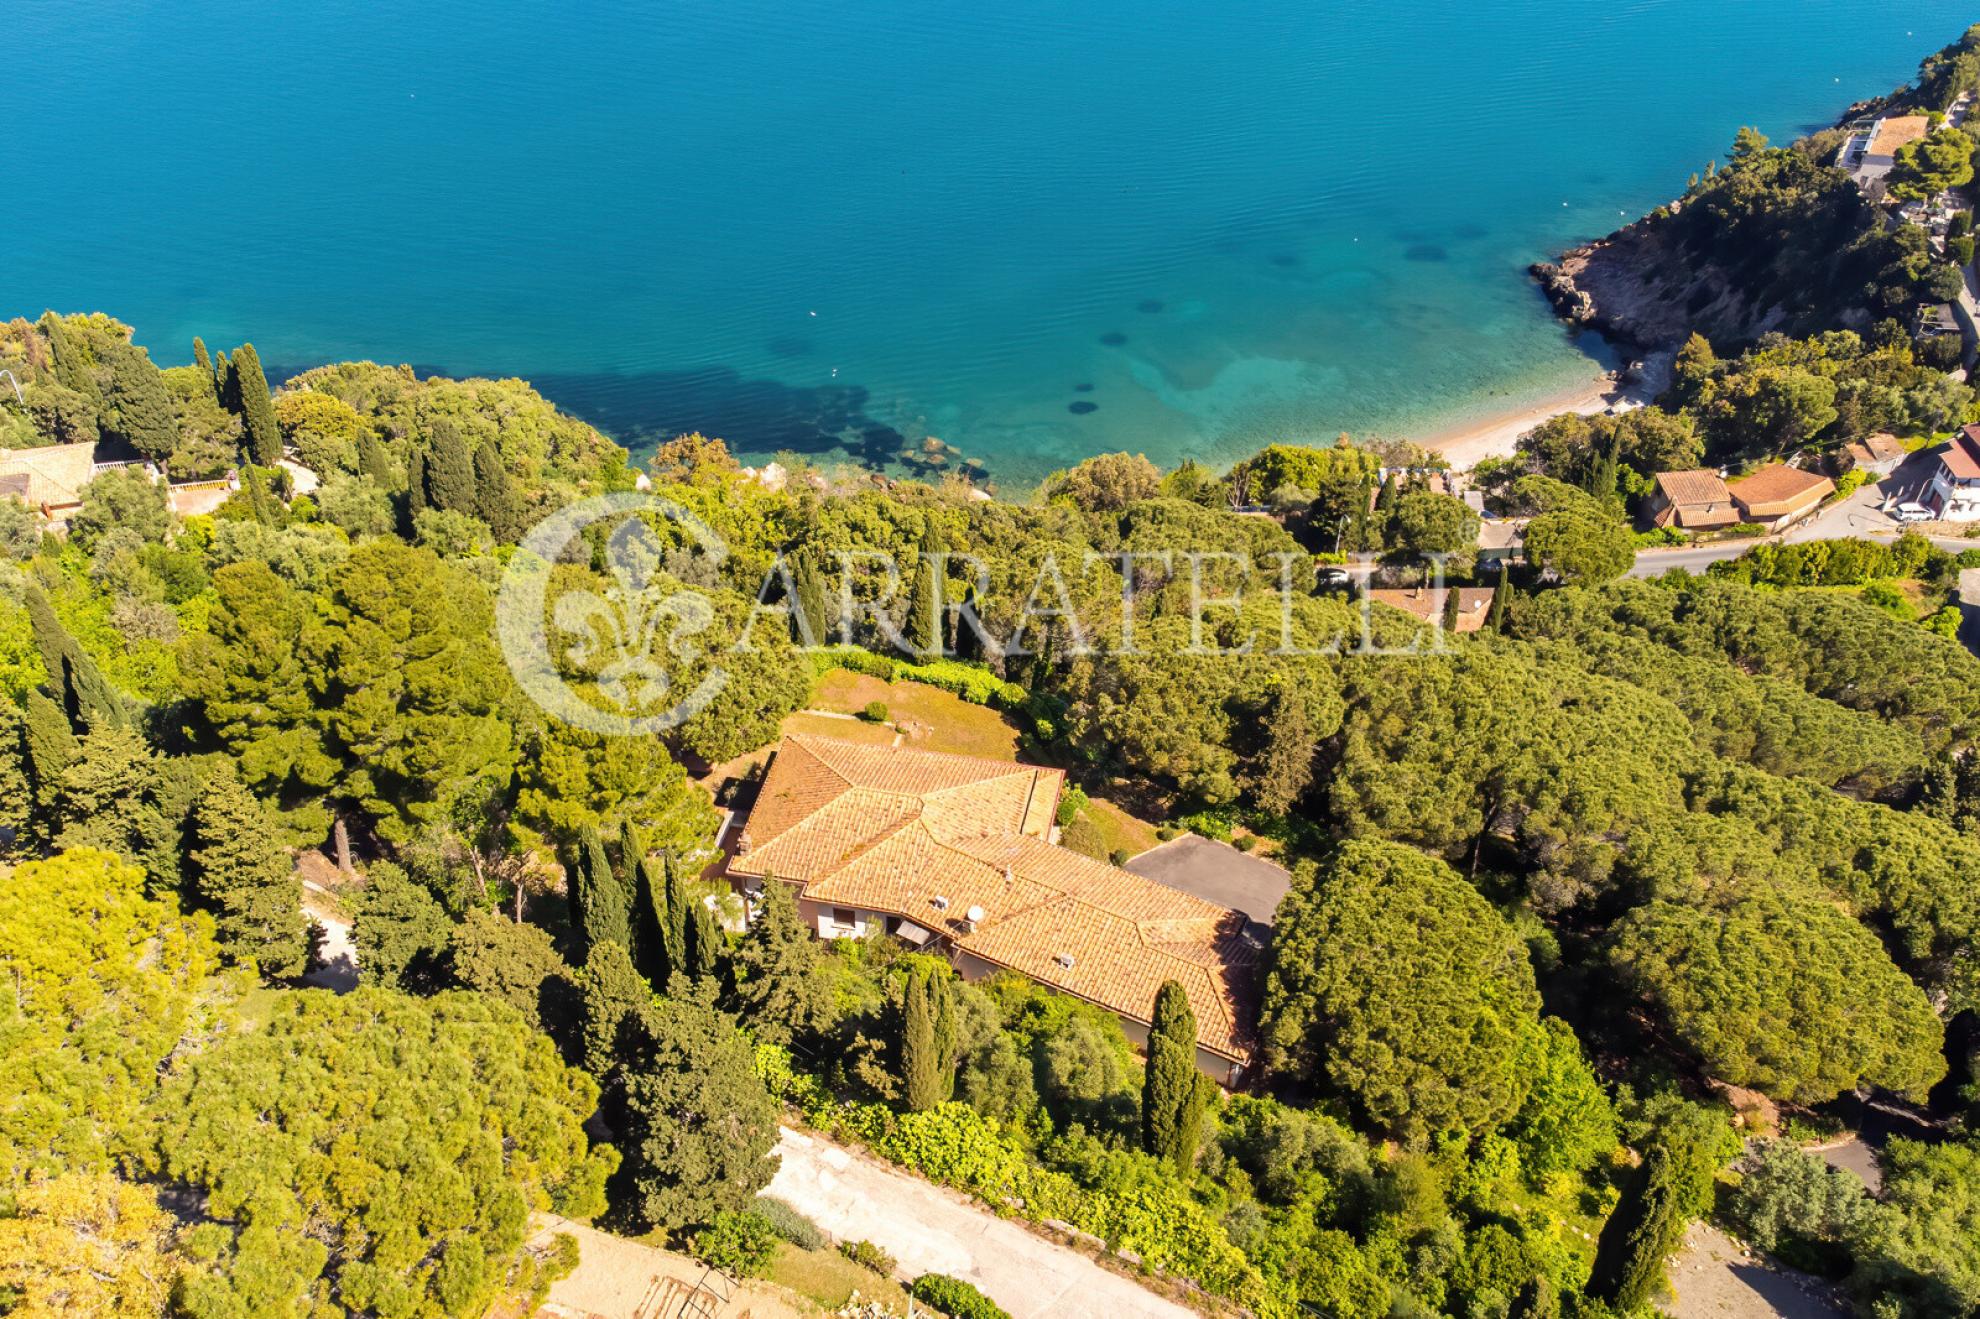
Prestigious seaside villa in Porto Santo Stefano, Tuscany
Stunning villa located near Porto Santo Stefano, boasting stunning panoramic views and captivating architectural features and a sense of privacy. Location The town, the capital of the Argentario peninsula, is a picturesque seaside village and a popular holiday destination since the time of Imperial Rome. The town of Porto Santo Stefano extends along its two ports. The larger, commercial port is the first one you encounter upon entering the town. Fishing boats dock there, as well as ferries to the islands of Giglio and Giannutri. The smaller Pilarella port is Porto Santo Stefano's favorite place for strolling and relaxing. It can be reached by walking along the seafront promenade designed by Giorgetto Giugiaro. Here, the tables of bars and restaurants overlook the sea, allowing you to sample local cuisine or relax with a drink while admiring the view of this enchanting seaside village. Description The villa has a surface area of approximately 900 square meters, is spread over two levels and comprises a large entrance hall, a spacious reception area with access to one of the panoramic terraces overlooking the sea, a dining room, a comfortable and functional kitchen, a staff area, and a large staircase leading to the upper floor. The upper floor comprises five comfortable bedrooms with bathrooms and walk-in closets; three of the five bedrooms can be considered true suites. Two of the bedrooms open onto a large panoramic terrace overlooking the sea. The ground floor living room leads to the immaculately maintained garden, planted with tall trees and a myriad of flowers, shrubs, hedges, and more. The reception area also leads to a large and pleasant veranda overlooking the sea, perfect for relaxing and enjoyable moments. The veranda leads to an annex consisting of a large room used as a hobby room and an outdoor kitchen area used for large receptions and the pizzeria. We can call it a pizzeria as it is an area equipped with ovens, counters, and everything else needed to bake delicious pizzas for friends. Outdoor spaces: In addition to the perfectly manicured garden, there is another courtyard area featuring countless fruit trees of all kinds. The property is fully fenced; access to the property is via a driveway preceded by a large gate. At the entrance to the property is another building divided into two apartments of equal size, currently used as a caretaker's lodge and a guest apartment. The total land, including the garden, is over 4 hectares. Condition and finishes: The property is in excellent condition, and all utilities are present and functioning. The exterior is finely stuccoed in white, while the interior features terracotta floors, finely decorated tiles, and high-quality parquet. Potential uses: This property is ideal as a vacation home or as a rental property during periods of absence.
7.500.000,00 €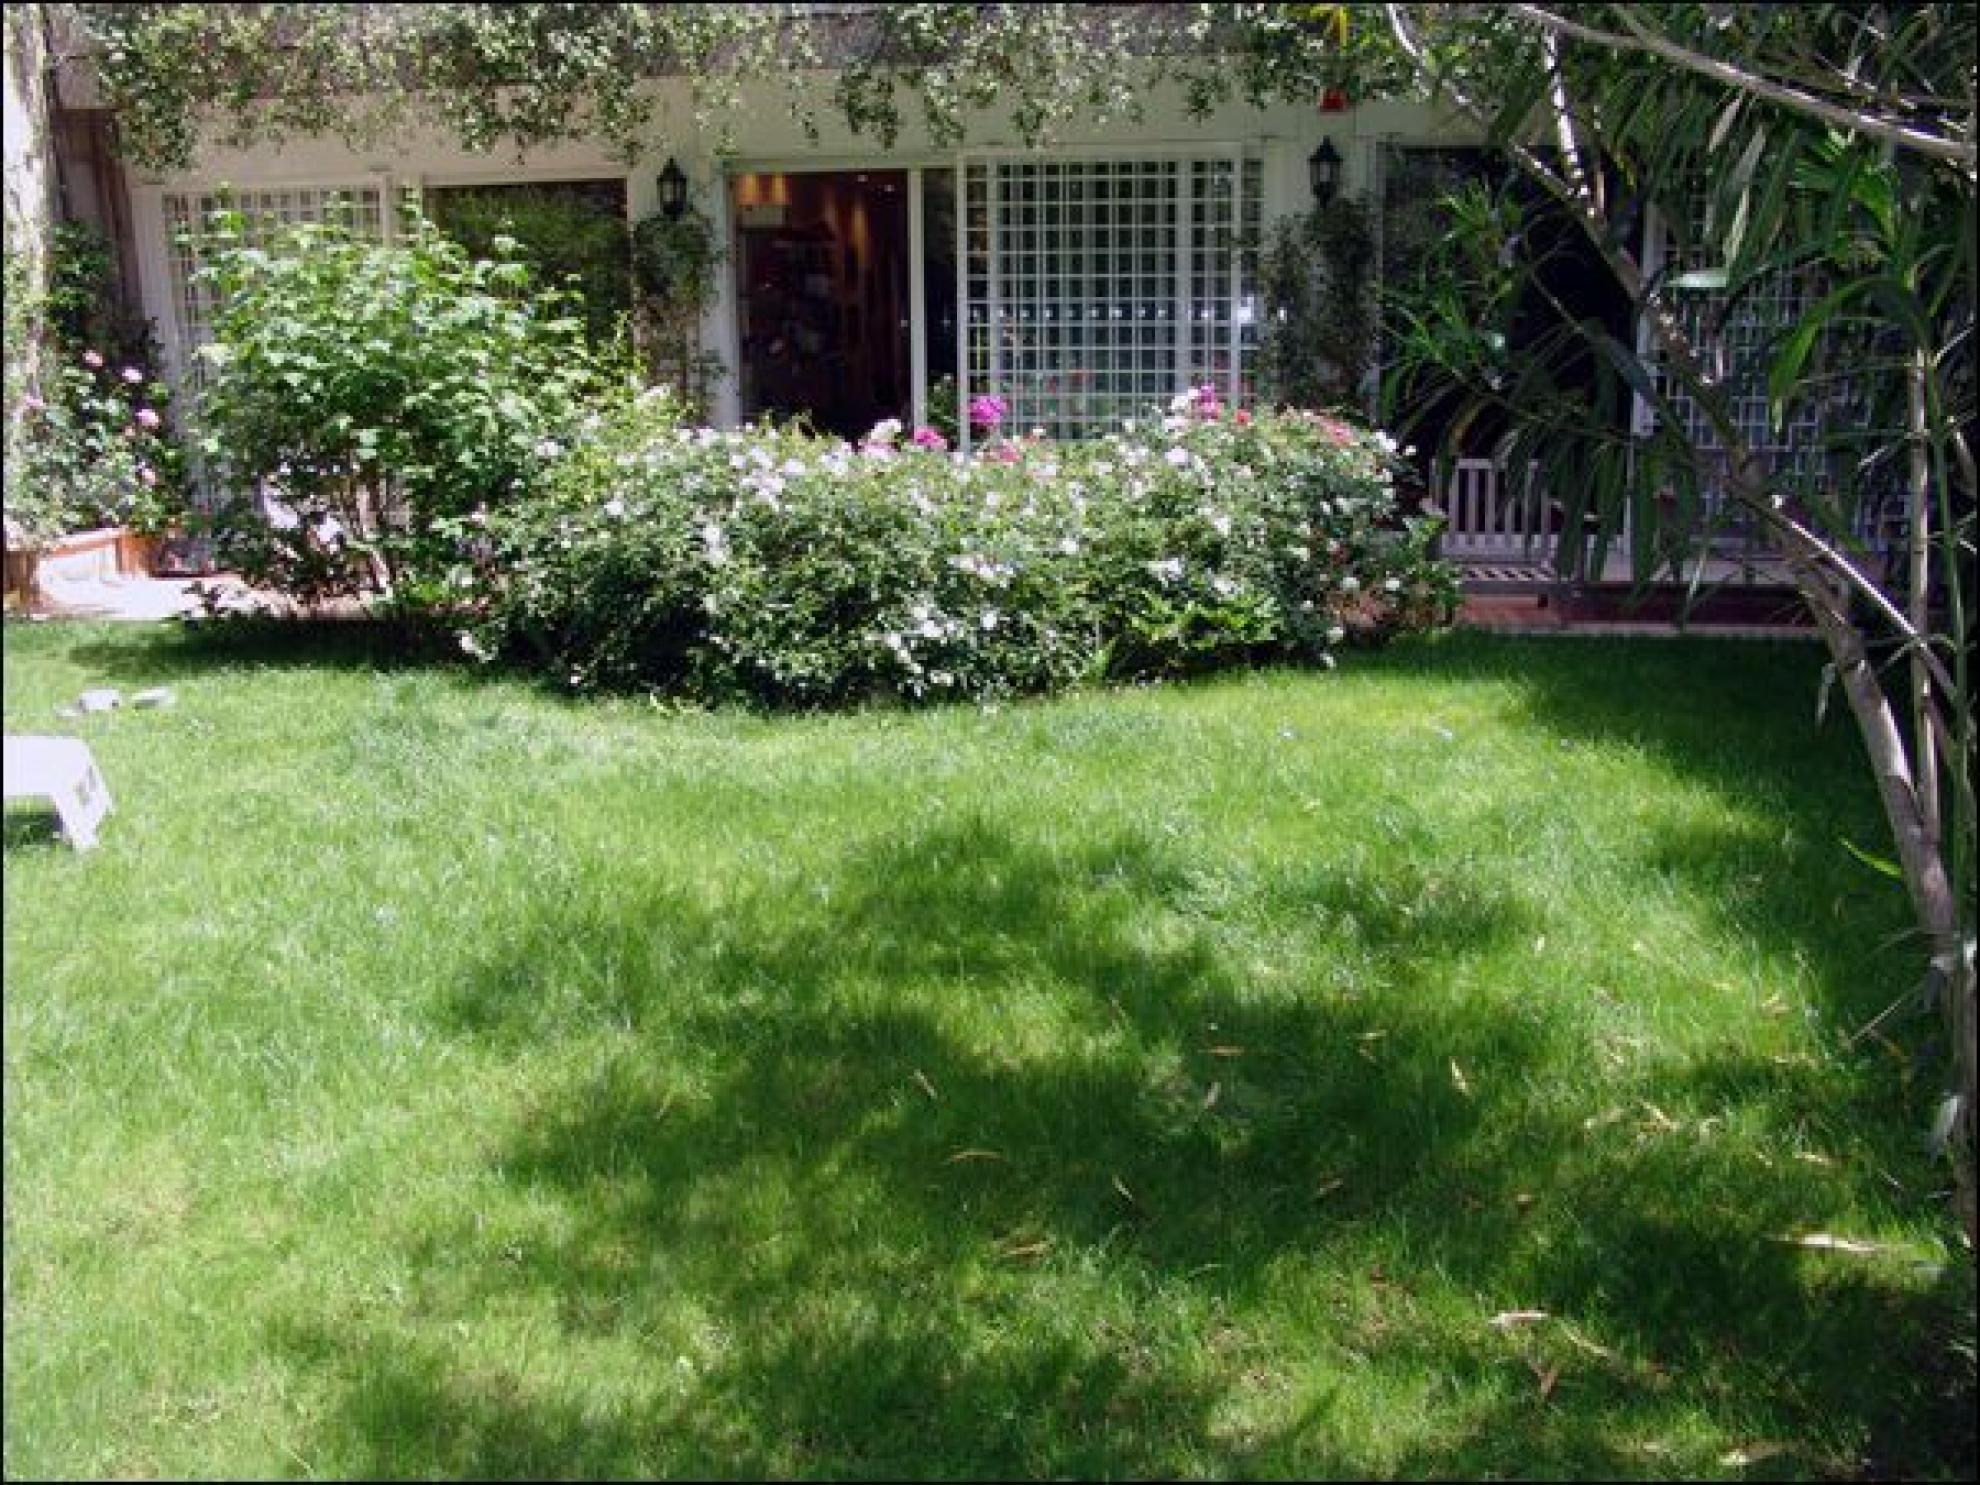
modern villa in Camilluccia
In the prestigious Vigna Clara neighborhood, Camilluccia area, in the Via Teheran district, this beautifully renovated, classic-style villa is spread over three levels, totaling approximately 500 square meters. It features an internal elevator, a garden, a terrace, and a garage. Location The three-level villa is located in the Roma Nord neighborhood on Via Teheran, within an exclusive complex with large green spaces available to condominium members, day and night security, and perimeter security during the month of August. It has a driveway with double barriers and a video intercom. The neighborhood is primarily residential, with the nearest shops (Vigna Clara) approximately 1 km away. Building Description The property is accessed via a pleasant driveway that, with a few steps, leads to a porch. From here, you enter the building, where a large entrance hall leads to the living area, consisting of a double living room and a dining area. Returning to the entrance hall, we find a guest bathroom, the elevator, and access to the large and comfortable kitchen, which also has a service entrance, elevator access, and is connected to the dining area. The bright double living room leads to the large, pleasant, southwest-facing terrace. A staircase and/or elevator leads to the sleeping area, where we find a first hallway, the master bedroom with bathroom, large built-in wardrobes, and access to the garden. There are also three additional bedrooms, two of which share a bathroom and also access to the garden, and one with its own en suite bathroom, adjacent to a pleasant living room that could also be converted into a fifth bedroom. The stairs and/or elevator continue down to a large hobby room, which, with extensive renovations, could even be doubled in size as excavation work could be carried out under the garden. The hobby room leads to the utility area consisting of a large laundry/ironing room, a guest bedroom and bathroom, and a cellar. There is also access to the garage, which can accommodate 3-4 cars. Outdoor Spaces The villa benefits from a large shared garden equipped with a children's playground, as well as a private garden. The living room leads to the southwest-facing terrace, which is habitable and equipped with a barbecue. Condition and Finishes All interior finishes are of excellent quality: stunning parquet floors in both the living and sleeping areas, beautiful ceramic tiles in the bathrooms, mosaics, a whirlpool tub, an alarm system, and air conditioning. The living area walls are in Venetian stucco. The fixtures are of excellent quality. Potential for Use. This property is ideal for a large family and/or those with discerning tastes regarding space, seeking classic interior finishes, who appreciate privacy, and who view living within a complex as a positive aspect in terms of security and pleasant outdoor spaces.
2.100.000,00 €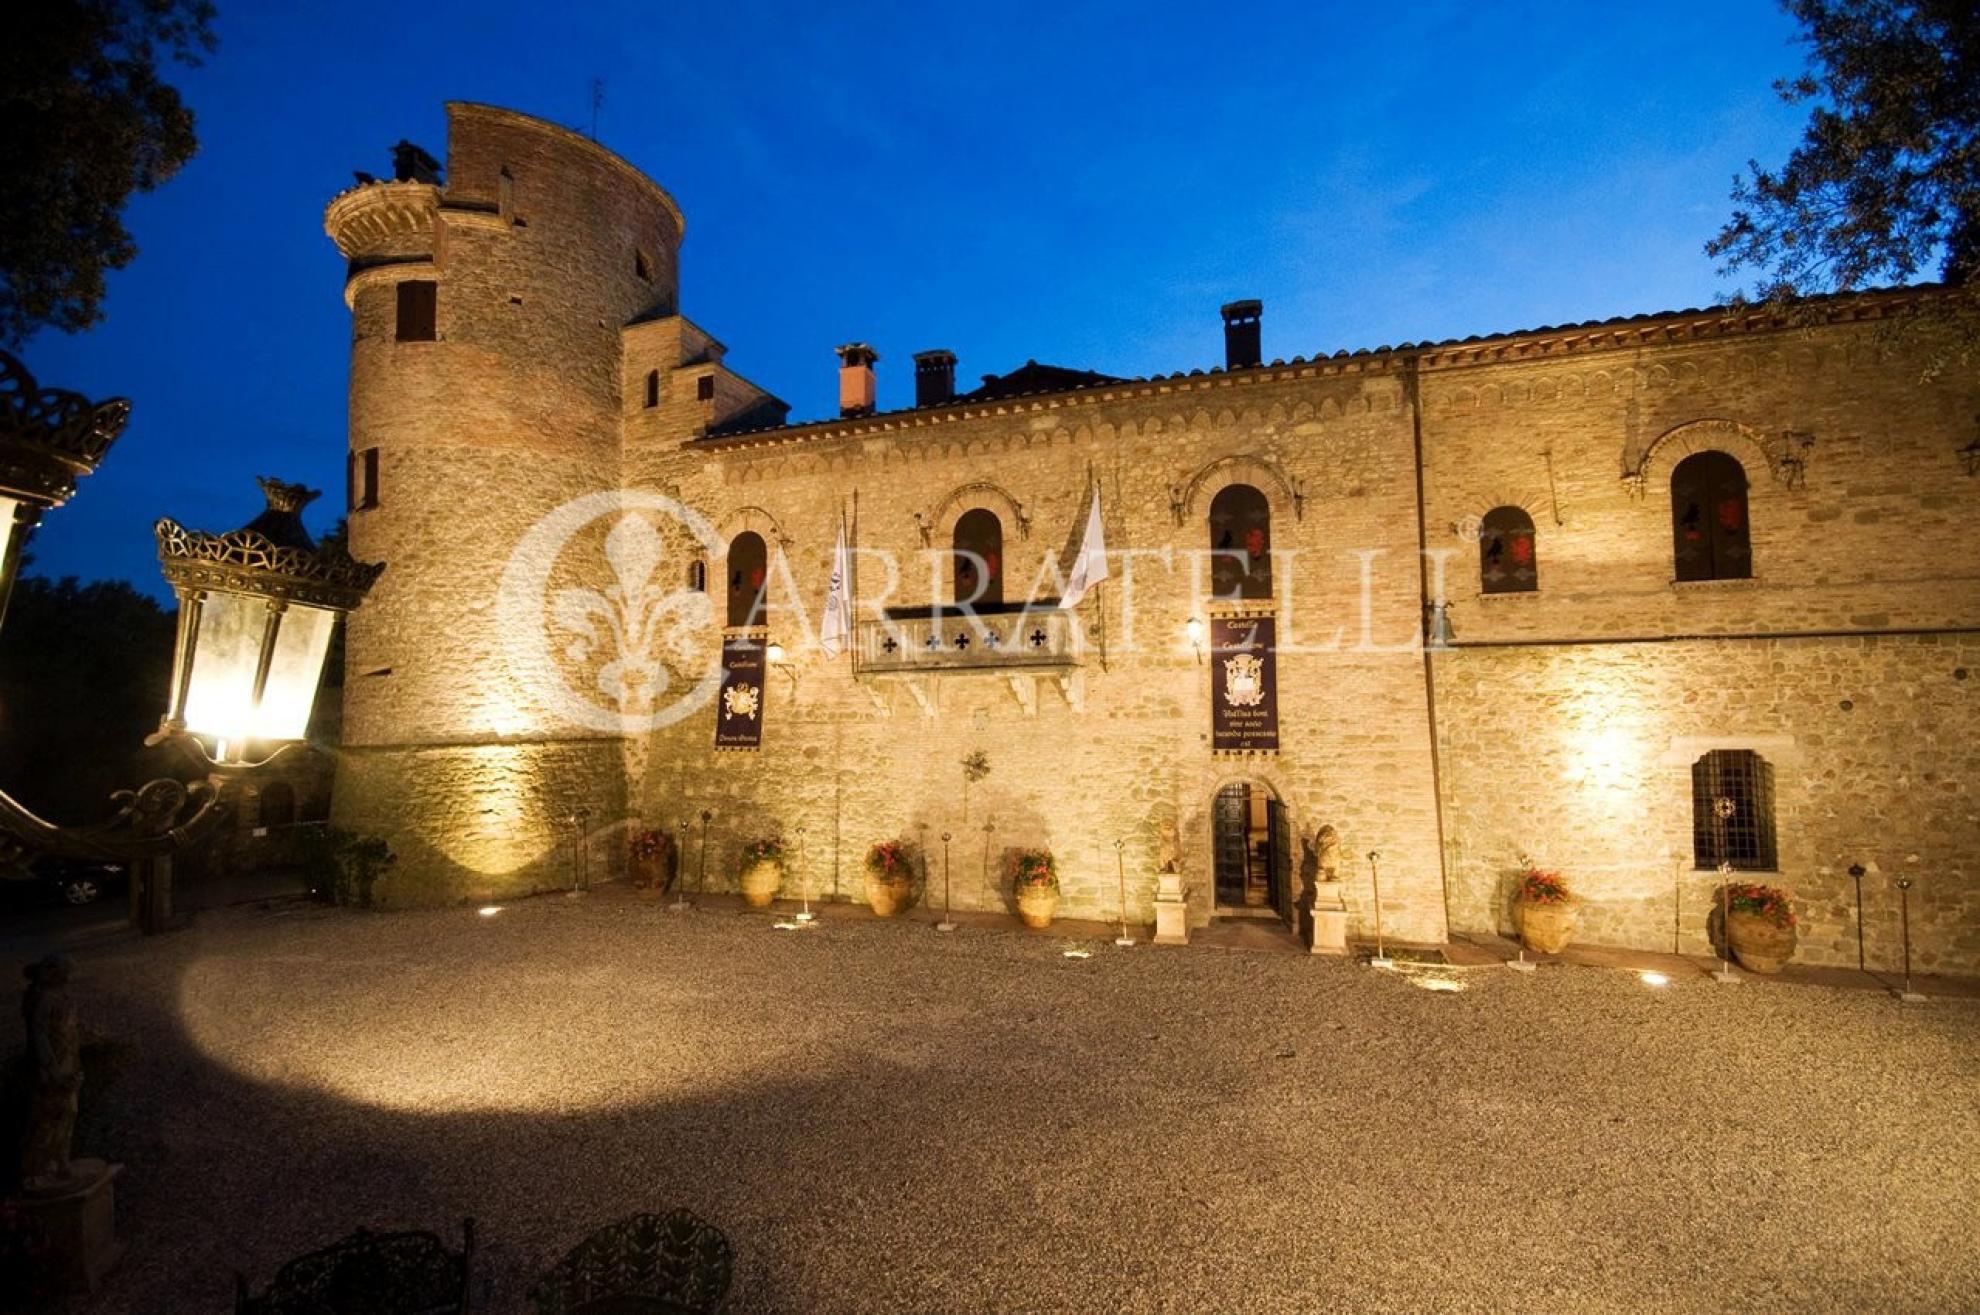
prestigious castle in Umbria
The Castle stands at approximately 500 meters above sea level in the municipality of Deruta (Perugia), at Via della Libertà 2. It can be reached from Deruta via the scenic hill road known as "Via di Castelleone," approximately 4.5 km from the capital. It is a historic, artistic, and architectural monument dating back to the 15th-16th centuries and is protected by the Superintendence for Artistic, Historical, and Architectural Heritage of the Umbria Region. Location Deruta's origins remain largely unclear. What is certain, however, is its ancient connection with Perugia, of which it has always been a valuable bastion to the south, toward Todi, a role still evidenced by its appearance as a fortified castle. Perugia is approximately 20 km away, as is its airport. Fiumicino Airport (Rome) is approximately 185 km away. Description The Castle is primarily composed of three original architectural nuclei representing three historical eras: Medieval (dating back to the 12th century), evident in the thick stone walls (sometimes over 2.5 meters thick) that converge in the large and imposing Lombard Tower (approximately 36 meters high, square in shape and divided into five levels). Renaissance (dating back to the 15th-16th centuries), which constitutes the main body of the Castle, consisting of its rounded Keep or Tower (divided into five levels) and joined to the main core of the Castle itself. Neo-Gothic (dating back to the 19th century), which represents the part of the building, joined to the Renaissance core, that overlooks the inner village and encloses the Belvedere Tower at its summit. The interiors consist of seven double bedroom suites with the option of a third bed, each with spacious bathrooms or salle de bain equipped with the latest technology, including hydromassage tubs and showers with aromatherapy, chromotherapy, ozone therapy, a Turkish bath, and radio. The suites are named Contessa, Dama Bianca, Borgia, Gotica, Vergini, Torre degli Sposi, and Cavaliere. The master apartments, spread over two floors, feature four double bedrooms with the option of a third bed (each with a private bathroom equipped as above): the Master Bedroom, the Bishop's Room, the Guest Room, and the Lady-in-Waiting's Apartment. In the Lombard Tower, there are four additional double bedrooms on four levels, called the Swan Room, the Lion Room, the Raven Room, and the Templar Room, connected by a spiral staircase. On the first level of the Lombard Tower, there are two fully equipped bathrooms. In the Castle's guest quarters, there are two rooms (one double and one single) with bathrooms equipped for disabled guests. In total there are eighteen bathrooms, including the one serving the Museum Area (called the Grottino), the one serving the Dining Room, the one called the Pensile dello Studiolo located in the Master Apartments, and the service bathroom adjacent to the Knights' Hall. The property features three fully equipped kitchens: the Old Castle Kitchen (on the ground floor), the Master Kitchen (on the first floor of the master apartments), and the kitchen of the small Lady-in-Waiting apartment (on the second floor of the master apartments). On the ground floor there are numerous reception rooms and halls, some of which are large, such as the Great Hall of the Armourers (over 100 m2, the largest in the Castle), the Old Captains' Refectory, the Grand Entrance to the Village and Renaissance Staircase, the Painted Neo-Gothic Hall, the Guard Room, the Armoury, the Small Passage Room and Grotto, the Old Gallery and main entrance to the Castle, the Gallery and Collections Room, the Entrance Hall to the Park with the underlying medieval underground tunnels that lead to the still-existing Old Medieval Cistern, the Great Renaissance Dining Room, the Old Castle Kitchen, and the Old Chapel. Connected to the Castle's Great Kitchen, a large, glass-enclosed portico leads to the Cloister's two covered rooms, which in turn connect to the Lombard Tower and its aforementioned rooms. A wide stone staircase leads to the Castle's Piano Nobile and the Countess, Borgia, White Lady, Gothic, and Virgin suites. From the Countess and Borgia suites, there is access to a large, square-shaped panoramic terrace overlooking the Castle's Old Cloister and internal courtyard. From the Lombard Tower, there is external access to the Castle's large external terraces overlooking the portico. From here, a bold stone staircase leads to the exposed summit of the Lombard Tower itself, which serves as a solarium. The Piano Nobile also houses the Golden Hall, the Ancient Library, the Office, and the Renaissance Hall, which leads to the Torre degli Sposi (the Wedding Tower), the Castle's main keep. The hall is divided into three levels: the Salle de Bain (completely frescoed), the Bridal Salon, and the aforementioned Torre degli Sposi suite. It is noteworthy that the entire Piano Nobile of Castelleone Castle, including the various connecting corridors, features fully decorated walls and ceilings, both in tempera and fresco, with geometric, naturalistic, romantic, and feudal military motifs, and so on, each room unique. From the Piano Nobile, you can access the aforementioned Knight's Hall and the Great Hall of the Knights, also entirely decorated in tempera on both the ceiling and walls. From this large reception room, a covered external staircase leads to the covered summit of the Belvedere Tower, which offers a 360-degree panorama. Outdoor Spaces The property's total perimeter is approximately 800 meters, encompassing three roads. The castle has nine entrances: three from the park (with large, automated, cuspated wrought-iron gates), one from the internal courtyard, one directly from the park located on the main façade of the building, three from the internal village on Via della Libertà, and one on Vicolo dell'Ulivo. The surrounding land measures approximately 8,500 square meters, predominantly planted with tall trees, almost all of which are centuries-old (oaks and holm oaks), and a park and garden with terraces sloping down to the 12.5 x 6 meter swimming pool located at the foot of the castle walls. The pool is equipped with an 8 square meter Jacuzzi tub with aroma and chromotherapy. Adjacent to the pool is a well made of stone and antique bricks. Condition and Finishes The property, consisting primarily of stone walls, antique exposed bricks, and plastered sections, extends over an internal surface area of over 2,000 square meters. usable space (plus approximately 500 square meters of attic space) extending across nearly 100 rooms. The internal cloister is enclosed in the northwest-facing part of the building, with another well-cistern in the center, made of ancient bricks, still in use. Cadastral classification of the entire castle area: D2 (commercial use). Cadastral classification of the private chapel alone: B7 (religious buildings). Potential for use: This prestigious castle is perfectly suited to being used as a charming luxury accommodation facility. It represents an investment dedicated to beauty, art, and history.
13.000.000,00 €